Climate & Sustainability Reporting
From regulatory requirement to audit-ready reporting.
From regulatory requirement to audit-ready reporting.
Australia’s mandatory climate-related financial reporting regime is being phased in. For many businesses, the challenge is not simply knowing that an obligation exists; it is establishing the data, methodology, processes, judgements, documentation and governance needed to produce reporting capable of external scrutiny.
What the service is — and is not
This is a compliance and reporting service. Keyspan is not engaged to tell a client how ‘green’ its business should be or to prescribe environmental strategy. The service helps management build the reporting framework, supporting analysis and evidence needed to meet applicable climate-related financial reporting obligations, working alongside the statutory auditor where appropriate.
The reporting challenge
Required information may sit across financial systems, operational systems, facilities, suppliers, business units and existing management processes. It must be identified, collected and assessed using an appropriate methodology. Assumptions and judgements must be understood; models constructed and challenged; and disclosures supported by evidence capable of review and assurance.
The objective is not simply to produce a report. It is to build a defensible reporting process behind it.
How we work with you
Scope
Understand the applicable reporting requirement, organisational boundaries, existing processes and responsibilities.
Map
Identify the required information, where it resides, who owns it and where gaps exist.
Collect
Work with client personnel to extract and organise relevant financial, operational and other source information.
Model
Build the reporting framework and apply the appropriate methodology, assumptions and calculations.
Challenge
Test calculations, assumptions, judgements and outputs; investigate anomalies and results that do not appear consistent with the underlying business.
Agree
Work through results with management and resolve outstanding questions and management judgements.
Support Assurance
Prepare the supporting analysis, documentation and evidence package and work with management and the statutory auditor through review and assurance.
Report
Support management in translating the agreed analysis and framework into the required statutory disclosure.
Scope
Understand the applicable reporting requirement, organisational boundaries, existing processes and responsibilities.
Map
Identify the required information, where it resides, who owns it and where gaps exist.
Collect
Work with client personnel to extract and organise relevant financial, operational and other source information.
Model
Build the reporting framework and apply the appropriate methodology, assumptions and calculations.
Challenge
Test calculations, assumptions, judgements and outputs; investigate anomalies and results that do not appear consistent with the underlying business.
Agree
Work through results with management and resolve outstanding questions and management judgements.
Support Assurance
Prepare the supporting analysis, documentation and evidence package and work with management and the statutory auditor through review and assurance.
Report
Support management in translating the agreed analysis and framework into the required statutory disclosure.
Where Judgement Matters
Not every stage is mechanical. Testing assumptions, resolving anomalies and agreeing judgements with management are where experienced judgement matters most — the process is built to support that, not replace it.
Statutory Auditor Involvement
By the time reporting is complete, the auditor already knows the methodology, the scope of what will be assured, and where the supporting evidence sits. We prepare the reporting framework and supporting evidence with the applicable assurance requirements in mind, and prepare a defined assurance scope statement — setting out precisely what is, and is not, covered — for provision to the statutory auditor ahead of the engagement. This is provided alongside a complete evidence package of contemporaneous records, so the auditor’s engagement is scoped efficiently rather than discovered as the work proceeds.
Management retains responsibility for the company’s reporting and judgements. The statutory auditor retains independent responsibility for the assurance conclusion, which — consistent with AASB S2’s phased approach — typically begins as limited assurance and may extend over subsequent reporting years.
Your auditor shouldn’t encounter your methodology for the first time at year end.
Australian reporting timetable
Group 1
First reporting period
2 of: >$500m revenue / >$1bn assets / >500 employees
Financial years beginning on or after
1 January 2025
Group 2
First reporting period
2 of: >$200m revenue / >$500m assets / >250 employees
Financial years beginning on or after
1 July 2026
Group 3
First reporting period
2 of: >$50m revenue / >$25m assets / >100 employees
Financial years beginning on or after
1 July 2027
*See our Insights section for detailed size thresholds and criteria.
Experience from markets that moved earlier
Nick’s specialist capability rests on two direct pillars of experience. The first is capital-markets facing: as CFO of an IDX-listed palm oil producer, he led the ESG disclosure and sustainability vetting process required by international underwriters and investors as a condition of Indonesia’s first plantation-sector global USD bond in over a decade — disclosure the transaction could not have proceeded without. The second is domestic and ongoing: he personally prepares the company’s annual Sustainability Report for submission to the Indonesia Stock Exchange, alongside the Annual Report, under Indonesia’s mandatory sustainability reporting regime for publicly-traded companies.
Australia’s requirement goes further on both counts: it extends beyond listed companies to any large business meeting the applicable size thresholds, and adds forward-looking climate scenario modelling as a mandatory disclosure element. That combination of hands-on reporting discipline and capital-markets-grade rigour is the foundation this service is built on — extended, through structured methodology and modelling capability, to meet a broader and more technically demanding requirement.
Specialist expertise. Flexible support.
Technical methodology and reporting can be led by the appropriate specialist expertise, while supporting work — data collection, analysis, documentation, modelling support and related activities — can be structured around the client’s needs using client personnel, Keyspan resources or a combination.
You are buying a reporting outcome — not necessarily another full-time employee.
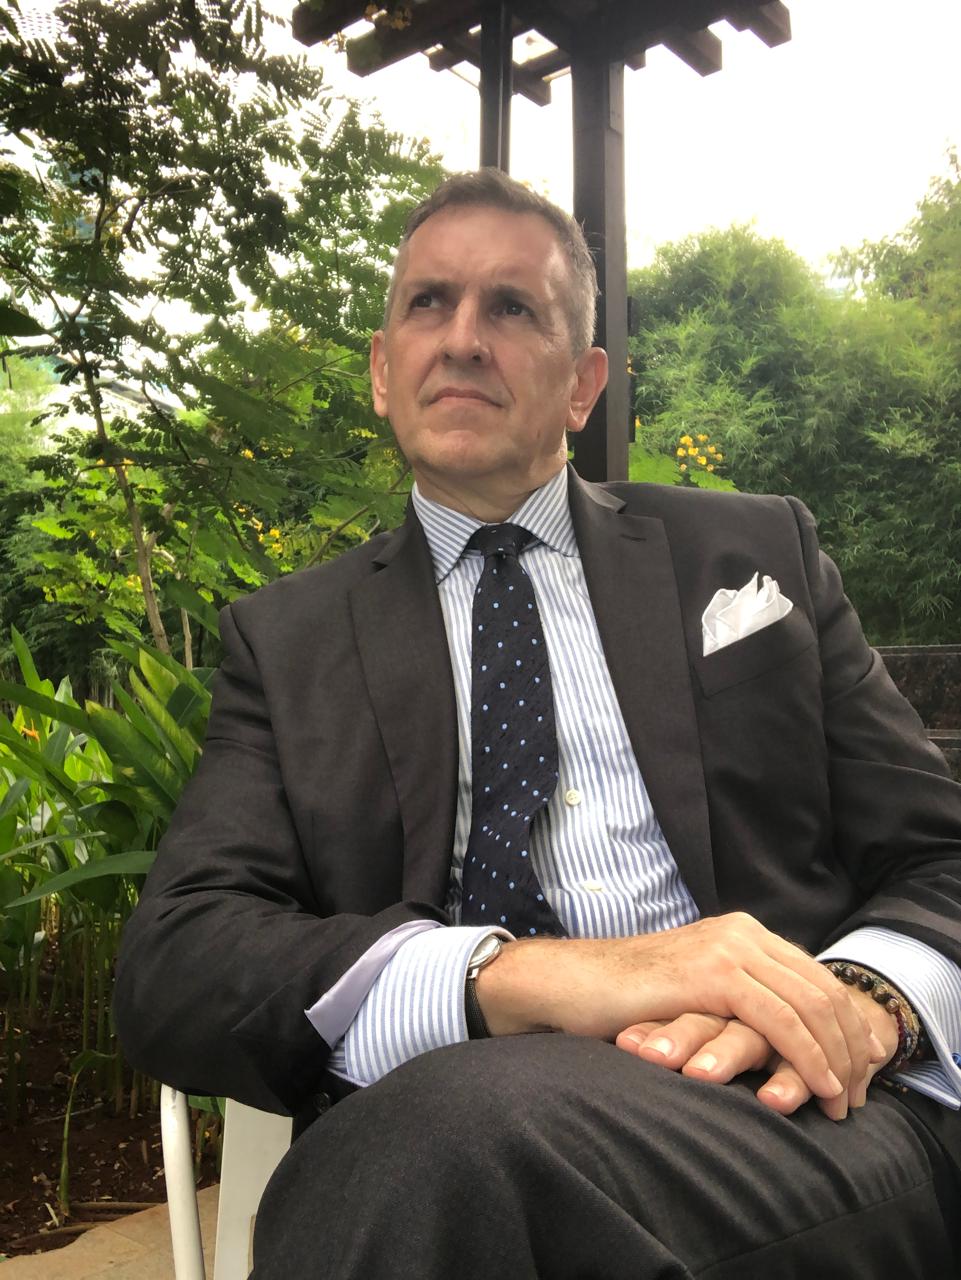
Nicholas J. Whittle
Alliance Partner, Climate & Sustainability Reporting
Nick holds an MBA from Columbia Business School and read Japanese Studies at Cambridge, and brings three decades of emerging-markets finance and governance experience across Indonesia and Southeast Asia. As CFO and Board Director of IDX-listed palm oil producer PT Sawit Sumbermas Sarana Tbk, he led Indonesia’s first plantation-sector global USD bond in over a decade, establishing new ESG benchmarks for Indonesian corporate sustainability. He currently chairs the Supervisory Board of PT CapitalInc Investment Tbk (IDX-listed).